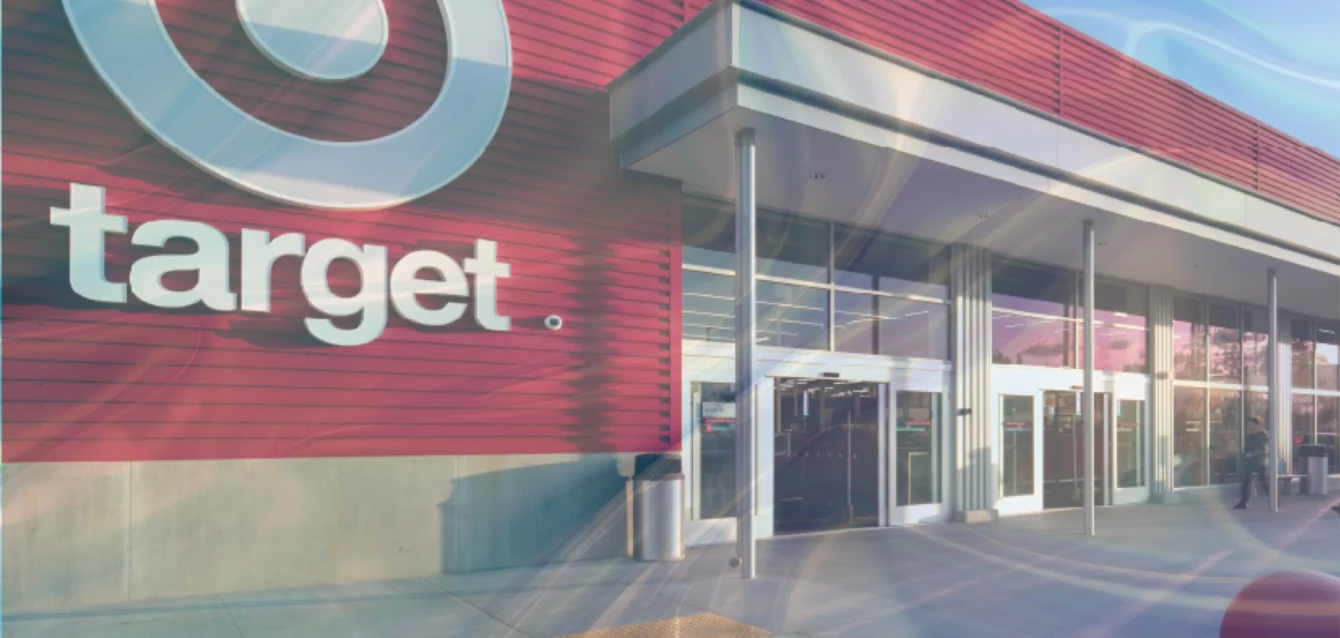
On April 20, Target confirmed it will open six new stores in May across Arizona, Missouri, New Jersey and North Carolina — the latest installment in a strategy aimed at adding 30 stores in 2026 and 300 by 2035. Five of the six new locations exceed Target’s 125,000 square-foot chain average, with two pushing close to 150,000. The footprint signals intent: Target is not testing small-format urban concepts here. It is planting full-scale anchor stores in markets it expects to carry the next decade of growth.
But behind the corporate fact sheet, the more interesting question for real estate, marketing and operations leaders is the one the press release does not answer: how strong are these markets actually performing right now?
We pulled foot traffic, demographic and competitor data on each of the six locations using PassBy Almanac, benchmarking each new Target site against the closest existing retail node — what we call a proxy market. The proxy gives us a real-world read on traffic volume, year-over-year momentum, and the competitive context Target will be walking into on opening day.
Here is what the data shows.
The six markets at a glance
| Target store | Proxy market used | Distance |
|---|---|---|
| Buckeye-Verrado, AZ | Verrado Way North Shops | 0.33 mi |
| Casa Grande Promenade, AZ | Promenade at Casa Grande | 0.18 mi |
| University City Olive Blvd, MO | Olive Boulevard Costco Area | 0.01 mi |
| Jersey City Route 440, NJ | Stadium Plaza Shopping Center | 0.05 mi |
| Myrtle Grove, NC | Carolina Beach Rd intersection | 0.04 mi |
| Selma, NC | St Mark Avenue Retail Hub | 0.19 mi |
Each proxy sits within a third of a mile of the new Target site — close enough that traffic, demographic and spend patterns translate directly to what Target should expect once doors open.
Volume tells one story. Momentum tells another.
The most proven retail node in this group is Casa Grande, AZ, with 3.87 million visits over the last 12 months at the Promenade — the closest thing to a guaranteed high-volume opening in the cohort. Jersey City and Selma follow at 2.4M and 2.36M respectively, while Myrtle Grove sits at the bottom with 1.19M visits, a smaller and more seasonal node.
But raw volume only tells half the story. The far more important signal for site selection teams is direction of travel — and there, the rankings flip almost entirely.
Looking at the last six months (October 2025–March 2026), University City, MO stands out as the cleanest growth story in the cohort, with foot traffic up 27.7% year over year and positive every single month. The Costco-adjacent location is benefitting from sustained household stock-up demand, and the closest competitor in the cluster — Costco itself — saw +7.7% YoY traffic over the same period, validating the broader market trend.
Buckeye-Verrado, AZ is the second momentum story, up 13.7% over the six-month window. The shape of that growth matters: November through January was soft, but February and March posted explosive gains of +41.7% and +39.1%. This is a market accelerating into Target’s opening, not coasting.
Casa Grande, despite its enormous traffic base, grew just 0.9% — stable but mature. Jersey City actually declined 2.6%, the only market in the cohort with a negative trend, though March showed a modest rebound.
Note: Selma, NC has been excluded from year-over-year comparisons. The site activated as a new retail node within the comparison window, producing a +244.6% YoY figure that is directionally positive but not analytically comparable to the established markets.
The Feb/Mar acceleration is the pattern to watch
When you break the YoY data down month by month, a clear pattern emerges across half the cohort: a soft winter followed by a sharp rebound entering spring.
Buckeye-Verrado went from -0.8% in January to +41.7% in February. Myrtle Grove flipped from -0.8% to +21.1% over the same period. Even Jersey City, the weakest market overall, swung from -2.9% in January to +2.5% in March. Only University City sustained strong double-digit growth across every month, while Casa Grande remained essentially flat throughout.
For Target, the implication is twofold. First, the markets it has chosen are entering opening season on rising traffic curves, which is a favorable backdrop for a store launch. Second, the variance across markets — University City growing consistently, Casa Grande stable, Jersey City struggling — means a one-size-fits-all opening playbook will leave performance on the table.
What the demographics and competitors say
Each of the six markets brings a distinct customer profile, and Target’s standard assortment is unlikely to be optimal everywhere.
Buckeye-Verrado is the strongest family-growth story in the cohort. Children aged 0–14 and adults 35–54 are heavily represented, household incomes skew mid-to-upper-middle ($75K–$99K is the largest band at 14.7%), and bachelor’s-degree attainment is higher than in nearby Casa Grande. Critically, there is no broad-line competitor in the immediate retail cluster — Target will likely become the first major anchor in the node. This is a market built for kids, grocery, household, school and drive-up.
Casa Grande is older and more mature, with the 45–59 age band dominant. The market is broadly middle-income, and Kohl’s — the closest department-store comp in the cluster — posted +4.3% YoY traffic over the same six-month window with positive growth every month. This validates Target’s opening environment as a proven, food-forward retail destination.
University City, MO combines midlife and family demographics with strong household stock-up behavior. Costco’s continued growth in the immediate cluster is the single best leading indicator we found across all six markets — household-trip retail in this corridor is structurally rising.
Jersey City is the urban outlier. The youngest profile in the cohort (25–39 dominant), dense, mixed-income, and oriented around frequent-trip daily-needs behavior rather than weekly stock-up runs. The closest comp, Acme Markets, is a high-volume grocery anchor that has softened slightly (-1.1% YoY). Target’s success here will depend on positioning around fresh food, pharmacy and convenience essentials rather than a traditional general-merchandise format.
Myrtle Grove is a smaller, seasonal coastal market with a mature family profile. There is no true Target-like comp in the immediate cluster, and the broader Wilmington trade area would need separate analysis to size the full opportunity.
Selma is the highest-traffic newly-activated retail node in the cohort, anchored by BJ’s Wholesale Club. The demographic profile skews more value-oriented, with a meaningful lower-income tail. Marshalls is the cleanest comparable benchmark in the cluster (essentially flat YoY) and suggests an essentials-and-stock-up positioning rather than a discretionary-led format.
The verdict
Looked at together, the six markets fall into three distinct opportunity profiles:
Highest-confidence openings: Casa Grande and University City. Casa Grande offers the largest proven traffic base with a positive Kohl’s comp; University City offers the cleanest momentum story in the cohort with a strongly performing Costco anchor next door.
Highest-upside openings: Buckeye-Verrado and Selma. Buckeye-Verrado is an emerging family-growth market with no anchor competition and accelerating late-period traffic. Selma is a high-traffic value market with a strong warehouse-club anchor, though the income profile and newness of the node warrant a more cautious assortment strategy.
Watch-list openings: Jersey City and Myrtle Grove. Jersey City has scale but a soft trend and an unconventional urban format challenge. Myrtle Grove is the smallest market in the cohort with limited comparable competition data — execution will hinge on local trade-area dynamics not visible in the immediate cluster.
For Target, the May opening cohort is a credible portfolio: a mix of proven volume, accelerating momentum, and emerging growth bets. For real estate teams at competing retailers, the cohort is also a roadmap — three of these six markets (Buckeye-Verrado, University City, and Selma) sit on traffic and demographic curves that will reward early entry from category specialists in grocery, off-price, fitness and household goods.
The full Almanac dataset behind this analysis covers foot traffic, demographic composition, spend indices and competitor benchmarks for every retail node in the US. If you’d like to see how your portfolio stacks up against Target’s May cohort — or run a similar pre-opening read on your own pipeline — get in touch.